
Portugal corporate loan interest: why rates are rising
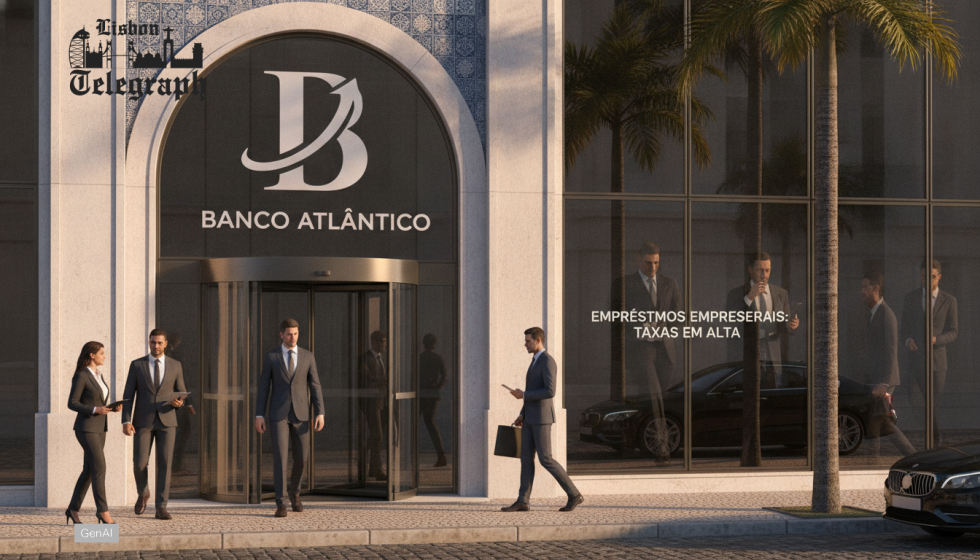
Portugal is seeing what market watchers call a fourth consecutive month of higher business borrowing costs. Corporate loan interest is being quoted higher as banks reconsider funding and credit risk in 2026. Lenders are saying higher wholesale benchmarks and wider risk premiums across the euro area, alongside stricter collateral and covenant expectations, are factors. Corporate finance teams also notice renewals more often include shorter fixed-rate windows, which can increase sensitivity to policy guidance and market volatility. Banks have signaled tighter standards in euro area lending surveys, explaining longer negotiations and more variable margins sector. Borrowers with weaker cash conversion cycles and concentrated customer exposure face the sharpest hikes, while exporters with hedged receipts generally get steadier pricing.
What higher borrowing costs mean for Portuguese businesses
Rising loan quotes are shifting day-to-day liquidity planning for firms relying on revolving facilities for inventory and payroll. When business lending rates rise, finance teams might delay supplier prepayments, extend payables, and renegotiate invoice terms to protect cash buffers. The pressure is reinforced market moves that affect bank funding costs, and related eurozone rates can influence pricing corridors for mid-sized manufacturers and logistics firms. In practice, spreads are diverging more between companies with strong reporting and diversified customers versus those with volatile demand.
Long-term implications for investment and refinancing
If tighter pricing sticks through 2026, it could shift capital allocation from debt-funded expansion to phased investment or higher equity buffers, according to corporate advisers following these markets. Higher corporate loan interest can raise the discount rate used in internal models, possibly lowering acceptable acquisition multiples and delaying equipment upgrades. Some CFOs are reconsidering maturity ladders to avoid refinancing clusters, especially if softer demand coincides with covenant step-ups. Global expectations matter because euro area banks watch dollar conditions and risk appetite; the Federal Reserve offers details in its Minutes of the Federal Open Market Committee, July 28 and 29, 2026. For context on how regulatory changes add costs in other sectors, this article is often cited in compliance discussions.
How to manage loan pricing and negotiate better terms
Companies are working to reduce perceived risk rather than rely solely on price concessions, say bankers and borrowers involved in renewals in Lisbon and Porto in 2026. Borrowers can improve reporting cadence, add security, and shift exposure to amortizing structures often considered lower risk banks. Treasury teams are tightening working-capital discipline with faster receivables collection, inventory rationalization, and selective capex deferrals. Scenario models stressing EBITDA, cash flow, and interest cover under higher benchmarks are becoming standard in credit committees. Some firms compare domestic offers with other policy-sensitive costs, including investment planning tied to residency-linked capital flows; these visa rules provide background influencing broader financing talks.
Outlook for corporate borrowing costs in Portugal
Bankers and economists suggest pricing will remain sensitive to policy guidance and asset-quality trends, especially in sectors exposed to energy costs and weaker external demand. Corporate borrowing costs could stay a visible measure of how quickly banks pass higher risk costs to the real economy, particularly for smaller borrowers lacking bond-market access. Analysts note the lag between policy signals and credit conditions, so tighter standards might persist even if benchmark rates level off. Domestic lenders watch arrears data and collateral valuations to decide on margins for renewals, say those familiar with credit monitoring. Firms that maintain covenant headroom and diversify funding sources should secure steadier terms as conditions evolve through late 2026.